PART 1
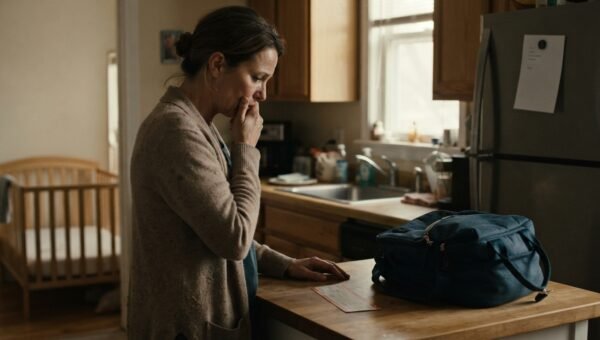
The cardboard boxes were stacked four high along the hallway of the home I lived in for twenty-two years. My knees ached from two straight weeks of wrapping Corelle plates in old newspaper and sorting through photo albums on the living room floor. I was fifty-eight years old, and my husband of twenty-nine years, Arthur, had spent the last six months telling me we were completely ruined.
According to Arthur, his commercial equipment supply business had taken a sudden, catastrophic downturn.
He sat at our maple kitchen table every night with his head in his hands, rubbing his temples until his skin turned red. He told me the debts were mounting, the creditors were calling his office at all hours, and he had no choice but to file for bankruptcy.
“It is the only way out, Evelyn,” he said to me back in April, staring down into his black coffee. “If we do not sell the house immediately to clear the outstanding debt, they will come after everything. We will lose the car. We will lose every nickel. We have to wipe the slate clean.”
The number he gave me was $120,000. He said that was the exact amount needed to settle the secured claims and keep him out of deeper legal trouble before the court proceedings finalized. We had bought our three-bedroom ranch in suburban Columbus back in 1997. The mortgage was paid off completely four years ago.
That house was supposed to be our peace of mind, our retirement safety net. Instead, Arthur listed it for a fast cash sale at $310,000, which was at least forty thousand dollars below market value. He claimed we needed a guaranteed buyer who could close in fourteen days flat.
I trusted him. When you have been married to a man since your twenties, you do not assume he is manufacturing a financial tragedy. I spent my afternoons crying quietly in the laundry room so he would not see how terrified I was of moving into a two-bedroom rental apartment on the other side of town.
Closing was scheduled for a Thursday morning at ten o’clock at the title company downtown. On Wednesday afternoon, less than twenty-four hours before we were supposed to hand over the keys, Arthur told me he had to run out to his storage unit to load up his power tools.
“Just finish packing the master bath,” he said, kissing my cheek with dry, tight lips. “I will be back by five. Tomorrow morning we sign the papers, pay off the balance, and we can finally breathe again.”
He took his truck and left. About forty minutes later, my cell phone rang on the kitchen counter. The caller ID showed the name of the buyer’s real estate agent, Brenda Collins.
“Hello, Evelyn?” Brenda asked. Her voice sounded clipped and rushed, the way closing agents get when a timeline starts slipping. “I am trying to reach Arthur, but his phone goes straight to voicemail.”
“He is out at our storage unit,” I said, wiping dust off my hands with a dish towel. “Can I help you with something?”
“We have a slight hold on the title package,” Brenda said. “The closing officer just ran the final title update before tomorrow morning, and we need your husband to sign the final release on the lien before the title insurance underwriter can authorize the wire transfer.”
I stood still in the middle of the kitchen. The refrigerator hummed against the silence.
“What lien?” I asked.
There was a pause on the line. Brenda rustled papers on her desk. “The private lien placed on the parcel two years ago. The payoff demand is for $120,000. It has to be cleared out of the gross proceeds tomorrow so the buyer gets a clean deed. Arthur was supposed to deliver the lender’s signed release yesterday, but we do not have it in the file yet.”
“A private lender put a lien on our house?” I gripped the edge of the counter. “Brenda, we paid off our thirty-year mortgage in 2022. We do not owe anyone money on this property.”
“Evelyn, it is right here on the county title search,” Brenda said gently, her professional tone softening into concern. “Recorded twenty-four months ago. A deed of trust in favor of an entity called Stone Creek Asset Holdings LLC. Look, let me email the scanned filing directly to your personal address right now. Take a look at it and have Arthur call me the second he gets back.”
My phone chimed two minutes later. I opened the PDF attachment on my small tablet screen.
It was a standard county recorder filing. The principal amount listed was exactly $120,000, secured against our home address. And at the bottom of the second page, on the line marked Authorized Signature for Borrower, was my name, Evelyn M. Vance.
Right next to it was the signature of the lender’s managing director.
I stared at that second signature until my eyes burned. The strokes were unmistakable. It had the sharp, slanted capital letter S with the looping tail, and the flat crossbar that dragged through the final letters. It was the exact same distinctive cursive Arthur used on our tax returns, on our joint checks, and on the anniversary cards he had given me for nearly three decades.
The cardboard boxes were stacked four high along the hallway of the home I lived in for twenty-two years. My knees ached from two straight weeks of wrapping Corelle plates in old newspaper and sorting through photo albums on the living room floor. I was fifty-eight years old, and my husband of twenty-nine years, Arthur, had spent the last six months telling me we were completely ruined.
According to Arthur, his commercial equipment supply business had taken a sudden, catastrophic downturn. He sat at our maple kitchen table every night with his head in his hands, rubbing his temples until his skin turned red. He told me the debts were mounting, the creditors were calling his office at all hours, and he had no choice but to file for bankruptcy.
“It is the only way out, Evelyn,” he said to me back in April, staring down into his black coffee. “If we do not sell the house immediately to clear the outstanding debt, they will come after everything. We will lose the car. We will lose every nickel. We have to wipe the slate clean.”
The number he gave me was $120,000. He said that was the exact amount needed to settle the secured claims and keep him out of deeper legal trouble before the court proceedings finalized. We had bought our three-bedroom ranch in suburban Columbus back in 1997. The mortgage was paid off completely four years ago. That house was supposed to be our peace of mind, our retirement safety net. Instead, Arthur listed it for a fast cash sale at $310,000, which was at least forty thousand dollars below market value. He claimed we needed a guaranteed buyer who could close in fourteen days flat.
I trusted him. When you have been married to a man since your twenties, you do not assume he is manufacturing a financial tragedy. I spent my afternoons crying quietly in the laundry room so he would not see how terrified I was of moving into a two-bedroom rental apartment on the other side of town.
Closing was scheduled for a Thursday morning at ten o’clock at the title company downtown. On Wednesday afternoon, less than twenty-four hours before we were supposed to hand over the keys, Arthur told me he had to run out to his storage unit to load up his power tools.
“Just finish packing the master bath,” he said, kissing my cheek with dry, tight lips. “I will be back by five. Tomorrow morning we sign the papers, pay off the balance, and we can finally breathe again.”
He took his truck and left. About forty minutes later, my cell phone rang on the kitchen counter. The caller ID showed the name of the buyer’s real estate agent, Brenda Collins.
“Hello, Evelyn?” Brenda asked. Her voice sounded clipped and rushed, the way closing agents get when a timeline starts slipping. “I am trying to reach Arthur, but his phone goes straight to voicemail.”
“He is out at our storage unit,” I said, wiping dust off my hands with a dish towel. “Can I help you with something?”
“We have a slight hold on the title package,” Brenda said. “The closing officer just ran the final title update before tomorrow morning, and we need your husband to sign the final release on the lien before the title insurance underwriter can authorize the wire transfer.”
I stood still in the middle of the kitchen. The refrigerator hummed against the silence.
“What lien?” I asked.
There was a pause on the line. Brenda rustled papers on her desk. “The private lien placed on the parcel two years ago. The payoff demand is for $120,000. It has to be cleared out of the gross proceeds tomorrow so the buyer gets a clean deed. Arthur was supposed to deliver the lender’s signed release yesterday, but we do not have it in the file yet.”
“A private lender put a lien on our house?” I gripped the edge of the counter. “Brenda, we paid off our thirty-year mortgage in 2022. We do not owe anyone money on this property.”
“Evelyn, it is right here on the county title search,” Brenda said gently, her professional tone softening into concern. “Recorded twenty-four months ago. A deed of trust in favor of an entity called Stone Creek Asset Holdings LLC. Look, let me email the scanned filing directly to your personal address right now. Take a look at it and have Arthur call me the second he gets back.”
My phone chimed two minutes later. I opened the PDF attachment on my small tablet screen.
It was a standard county recorder filing. The principal amount listed was exactly $120,000, secured against our home address. And at the bottom of the second page, on the line marked Authorized Signature for Borrower, was my name, Evelyn M. Vance.
Right next to it was the signature of the lender’s managing director.
I stared at that second signature until my eyes burned. The strokes were unmistakable. It had the sharp, slanted capital letter S with the looping tail, and the flat crossbar that dragged through the final letters. It was the exact same distinctive cursive Arthur used on our tax returns, on our joint checks, and on the anniversary cards he had given me for nearly three decades.